What is Mutual Fund: Definition, Benefits & How to Invest in it
- 3rd September 2026
- 04:00 PM
- 19 min read


A mutual fund pools money from many investors and invests it in stocks, bonds and other securities.
Mutual funds have become one of the most popular investment options in India, and the numbers are there to show it. As of July 2026, the total assets under management (AUM) of Indian mutual funds stood at ₹85.76 lakh crore, and it’s only increasing.
As an investor, whether you want to ensure your lump sum grows, or invest an amount as small as ₹100 each month, save on taxes, or take out a loan against your existing mutual funds, a mutual fund is indeed one of the most accessible and easy ways to invest money. Mutual funds also offer a wide variety of choices and risk levels.
What is a mutual fund and how it works?
A mutual fund is a diversified financial portfolio that collects funds from investors with similar goals.
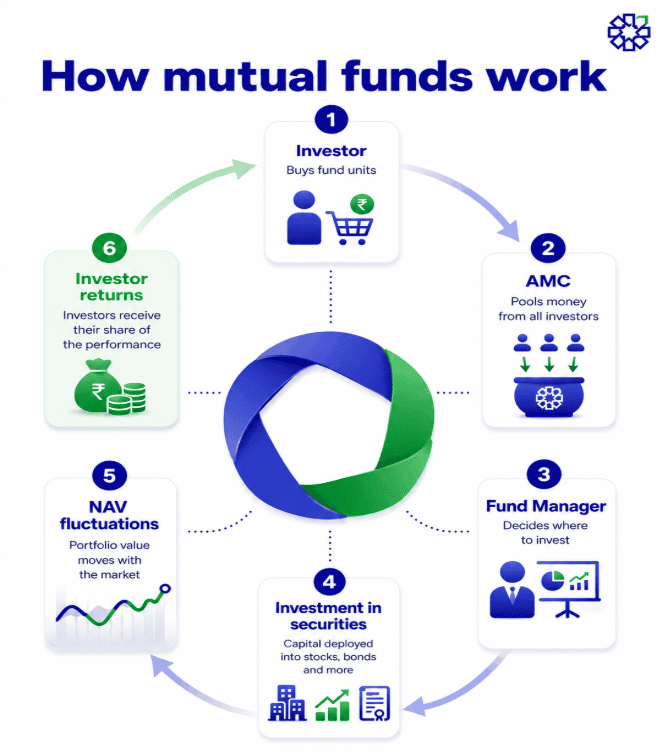
1. Asset Management Companies (AMCs) start schemes: These are firms registered with the Securities and Exchange Board of India (SEBI) that set up and run mutual fund schemes. A new scheme is launched through a New Fund Offer (NFO), a limited window during which units are at a fixed price of ₹10 each.
2. In exchange for your investment, you receive fund units: Once the NFO closes, units are no longer sold at that fixed ₹10 price, instead, their value is tracked through the Net Asset Value (NAV).
Calculated as: NAV = (total assets − total liabilities) ÷ total number of units.
For example, say mutual fund A holds the below Assets under Management (AUM):
₹700 in stocks
₹200 in bonds
₹50 in cash
₹20 in receivables (dividends and interest accrued)
₹70 in liabilities (fees and expenses)
90 units currently held by investors
NAV = (700 + 200 + 50 + 20 − 70) ÷ 90 = 900 ÷ 90 = ₹10 per unit
3. Professional Deployment: Each mutual fund is managed by a fund manager, who invests the pooled capital, buying into the chosen stocks, bonds, treasury bills and other securities.
4. Valuation & NAV Updates: The portfolio’s value moves up or down as it earns dividend income, interest income, and gains or losses. NAV is declared once a day, after the market closes at 3.30 pm, and reflects the value of the securities held in the fund.
5. Regular Reporting: AMCs provide regular updates about a scheme’s performance and any changes in strategy, available on the fund’s factsheet on the AMC’s website.
6. Redemption and Exit: When you want to claim your returns, you sell your units back to the AMC at the prevailing NAV. An exit load fee may apply for premature withdrawal.
Benefits of Mutual Funds
- Professional Management: The fund is managed by experts at a SEBI-registered AMC, who have thorough knowledge and experience of the markets.
- Portfolio Diversification: Mutual funds offer diversification across your portfolio, with exposure to various sectors and types of securities. Loss in one security or sector can potentially be offset by gains in others, which helps reduce concentration risk, though mutual funds remain subject to overall market risk.
- Liquidity: Mutual fund investments are easy to liquidate in case of emergency before the term, within 1-3 working days (T+1 to T+3) at the current market value (NAV). A loan against mutual funds also allows you to borrow using your mutual fund units as collateral.
- Affordability: An investor does not need large capital. Using a Systematic Investment Plan (SIP), you can start investing with as little as ₹100 to ₹500 every month.
- Transparency: Investors can view NAV and track the performance of their mutual fund daily. A statement of its portfolio is also released every month.
- Tax Benefit (Equity): Profit earned on equity mutual funds held for more than 12 months is called long-term capital gains (LTCG), taxed at 12.5% above ₹1.25 Lakh a year. Equity Linked Savings Scheme (ELSS) mutual funds also offer a tax benefit, if the old tax regime is selected, subject to the Section 80C limit of ₹1.5 Lakh.
- Flexibility: An investor can choose between methods of investing, such as Systematic Investment Plans (SIPs) and Lump Sum. There are also Systematic Transfer Plans (STPs), which move money from one mutual fund to another, and Systematic Withdrawal Plans (SWPs), which pay out money to you at intervals of your choosing.
Risks of Investing in Mutual Funds
- Mutual fund investments are subject to market risk, as market forces can cause a scheme’s NAV to rise or fall. Past performance is not indicative of future returns, and dividends are not guaranteed.
- In debt funds, credit risk is the possibility that a borrower will fail to repay a loan when due.
- There are over 1,400 active mutual funds at any given time in India, which makes it difficult to choose according to goals and risk appetite.
- In debt funds, interest rate risk means bond prices usually move opposite to interest rates, so rising rates lead to declining bond prices.
- Liquidity risk is when certain mutual funds find it difficult to buy or sell securities quickly at a fair price during periods of extreme market volatility.
- In actively managed funds, fund managers make market calls, which have the potential to be wrong and underperform, even with all their expertise. There is also the potential for loss, as markets are volatile. Events like geopolitical tensions, climatic conditions, etc., are completely out of their control and happen suddenly.
- High expense ratios and other management fees and costs can reduce overall returns
- Some mutual funds, such as ELSS or close-ended schemes, come with a lock-in period, during which you cannot redeem your investment at all, even in an emergency.
Types of Mutual Funds in India
Mutual Funds by Asset Class
An asset class is a category of investment, such as stocks, bonds, or cash. The table below shows what each type of mutual fund invests in.
| Fund Type | What It Holds | Risk | Ideal Horizon | Who It Suits |
| Equity Funds | Stocks, min. 65% of fund value. Sub-types: Large Cap, Mid Cap, Small Cap, Flexi Cap, Sectoral | Very high | 5+ years | Growth-focused investors, high risk tolerance |
| Debt Funds | Bonds, government securities, corporate debt | Lower, not risk free | 1-3 years | Conservative investors |
| Liquid Funds | Debt instruments, up to 91-day maturity | Low | Days to months | Parking surplus cash |
| Short Duration Funds | Debt instruments, 1-3 year Macaulay duration | Low to moderate | 1-3 years | Conservative, slightly longer horizon |
| Gilt Funds | Government securities | Low default risk, interest rate risk | Varies by scheme | Conservative investors |
| Hybrid Funds | Equity and debt mix | Moderate | Medium to long term | Growth with relative stability |
| Solution Oriented Funds | Goal based mix, usually locked in | Varies | 5+ years,
lock-in |
Retirement or child’s education savers |
| Index Funds | Tracks a market index, e.g. Nifty 50 | Very high | 5+ years | Low-cost passive equity investors |
Mutual Funds by Structure
Segregated by trading format how they can be bought, sold, and held.
| Fund Type | How It Works | Buying and Selling | Who It Suits |
| Open-Ended Funds | No fixed maturity, most flexible | Buy or sell on any business day | Most investors, including SIP investors |
| Close-Ended Funds | Fixed maturity, 3 to 15 years | Units only during the NFO, held until maturity | Investors comfortable with a lock-in, who won’t need to withdraw before the period ends. |
| Interval Funds | Mix of open-ended and close-ended | Buy or sell only during specific windows set by the fund manager | Investors comfortable with limited liquidity windows |
| ETFs | Tracks a market index, trades like a stock e.g. BSE Sensex Index | Bought and sold on the exchange in real time, needs a demat account | Investors wanting index exposure and lower costs, comfortable trading via exchange |
What Fees are charged by Mutual Funds?
Investing in mutual funds comes with certain costs that investors should be aware of.
Expense Ratio: The expense ratio is the annual fee charged by fund houses for managing your mutual fund investments. It primarily includes administrative costs, fund management fees, and marketing expenses. Equity funds range from 1% to 2.5%, debt funds are lower, from 0.5% to 1.5%, and index funds and ETFs carry the lowest expense ratios, around 0.1% to 1%.
Brokerage Charges: If you invest in mutual funds through a stockbroker or third-party app, you may have to pay additional brokerage charges. Some offer direct mutual funds.
Exit Load: An exit load is a fee charged when you redeem mutual fund units before the Lock-in-period is over. Equity funds charge 1% if you exit within 1 year, debt funds charge 0.5% if you exit within 6 months, and liquid and overnight funds carry no exit load.
Securities Transaction Tax (STT): For equity-oriented mutual funds, an STT of 0.001% is levied on redemptions.
Who Should Invest in Mutual Funds?
Mutual funds are a great option for:
Beginners: Investors who are at the beginning of their investment journey do not have enough knowledge about the stock market.
Salaried Investors: They can invest a portion of their salary each month through a SIP.
Retirement Planners: Mutual funds can help in creating a corpus for retirement. Systematic Withdrawal Plans (SWPs) are a good option to receive a fixed amount each month for expenses once you retire, while the rest stays invested.
Wealth Creators: People who have a goal in mind, such as buying a new car, renovating their house, or another long-term goal, can use mutual funds to work towards it.
Short-Term Goals: Likewise, if you have short-term goals like saving up for a holiday or buying jewellery, you can start a SIP to help build towards the required amount, while your money has the potential to earn returns along the way.
Modes of Investing in Mutual Funds
Mutual funds offer two main modes of investing: Systematic Investment Plans (SIPs) and Lump Sum. SIP is preferred by salaried individuals, as they usually have a regular income. A lump sum meaning for example you get a big bonus, or earn profits as a businessperson, and want to invest the whole amount in one go.
SIP (Systematic Investment Plan)
SIP allows an investor to make smaller, regular instalments, commonly every month, though you can also choose every quarter. An investor chooses how much money they want to invest each time and how often they want to make these investments. One of the benefits of a SIP is that it allows an investor to benefit from rupee cost averaging, that means more units of a mutual fund are bought when the price is low and fewer when it is high.
Note: Rupee cost averaging does not guarantee profits or protect against losses.
Calculate SIP Returns with the help of our SIP Calculator.
Lump Sum
A Lump Sum investment is when you invest a onetime amount. Your entire capital goes to work from day one. An investor can also potentially enter at the wrong time and suffer temporary losses. Lump Sum can be a suitable option for long-term investors.
Note: Mutual fund returns are not guaranteed
Calculate your potential lump sum returns with our Lump Sum Calculator.
SIP vs. Lump Sum
| Parameter | SIP | Lump Sum |
| Investment pattern | Recurring at regular intervals | Single investment |
| Market timing risk | Low risk | High risk |
| Financial discipline | High | Low |
| Best for | Salaried individuals, people with less money to spare | Bonus recipients, retirees, or anyone with surplus savings looking to invest |
Things to Consider Before Investing in Mutual Funds
- Risk Tolerance: Do you want low-risk, low-return funds, or are you a risk taker who wants to speculate on the market and potentially get bigger gains?
- Investment Horizon: What is your investment time frame? Short-term investors are usually better suited to debt funds, while long-term investors can invest in equity funds.
- Financial Goals: What are you going to use your returns for? Every investor should have a plan a purpose for their investments and track their progress.
- Expense Ratio: What is the expense ratio of your mutual fund? The annual fee an AMC charges, expressed as a percentage of your investment. Direct plans have a lower expense ratio than regular plans, since they exclude distributor commissions. Roughly, passive funds cost 0.05% to 0.50%, actively managed direct plans 0.50% to 1.15%, and actively managed regular plans 1.35% to 2.25%.
- AMC and Fund Manager: How has the fund performed compared to its benchmark? Benchmark is a market index used to judge fund performance
- Portfolio Composition: Check what the fund invests in and whether it matches your financial needs and values. Some investors, for example, prefer to avoid sectors like alcohol or defence. Compare its long-term performance against its benchmark rather than judging it on short-term returns alone.
How to Invest in Mutual Funds?
- Select a Platform: Open an account directly through an AMC, or through third- parties like a bank, online investment platforms or mobile apps. Register yourself by providing, information like name, address, email and phone number.
- Complete KYC: Submit your PAN, Aadhaar, address proof, and photograph to meet regulatory requirements and confirm payment method.
- Goals and Risk: Match your timelines and risk tolerance to the fund type, equity, debt, or hybrid. Choose a fund, which helps with your goals. Look at a fund’s past performance over the long term (3- and 5-year average returns also check the funds expense ratio which can eat into your returns over the long run.
- Make the Payment: Complete the transaction securely using net banking, UPI, or an auto-debit mandate.
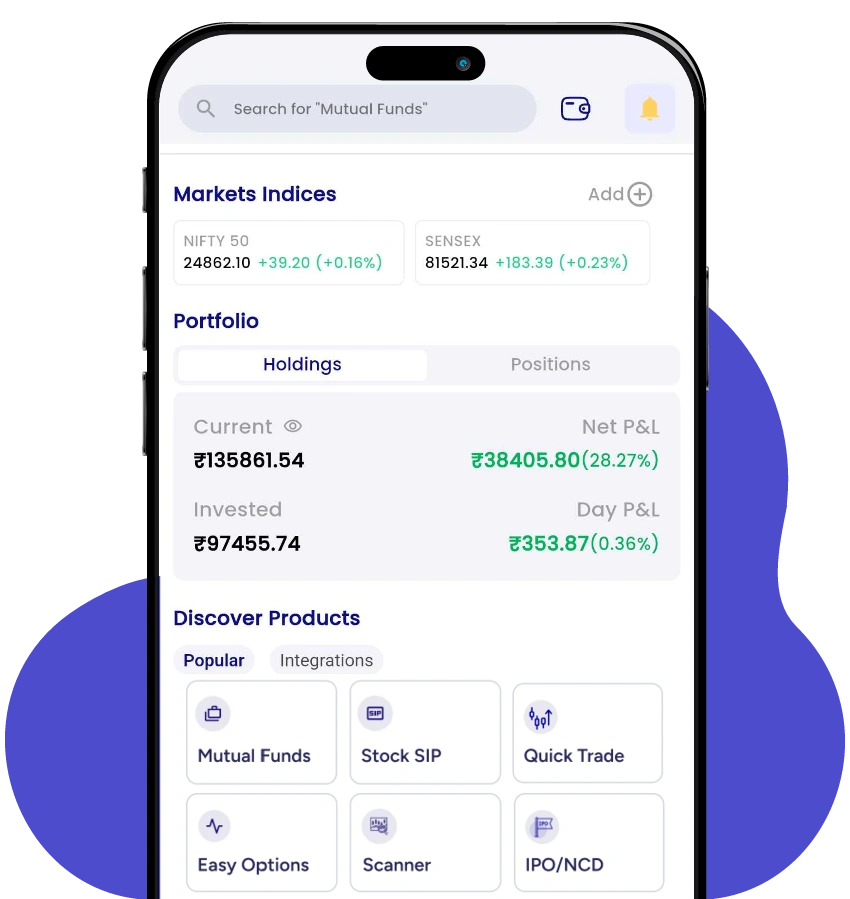
You can invest and track your mutual fund on the PL Capital app. Download it on Google Play or the App Store, or visit our mutual funds .
How to Manage Your Mutual Fund Portfolio?
Managing a mutual fund portfolio includes a few key points:
Asset Allocation: Allocate your portfolio across different asset classes based on your financial goals and risk tolerance. Investors who don’t mind risky investments tend to allocate a bigger part of their portfolio to equities.
Rebalancing and Review: At least once a year, check whether your funds still match your risk and return expectations by comparing their performance to a benchmark. For example, Nifty 50 TRI. If your asset allocation has drifted, say your equity allocation has grown to 80% because the stock market has performed well, rebalance by selling some equities and buying bonds to get back to your target, such as 70% equities and 30% bonds. Rebalancing this way lets you buy low and sell high.
Goals and Exit Strategy: As you approach your financial goal, move more money to liquid funds, so you don’t have to sell your equities if the market declines. You can use an STP (Systematic Transfer Plan) to get out of a declining market.
Mutual Funds vs Fixed Deposits vs Stocks
| Parameter | Mutual funds | Fixed deposits | Stocks |
| Nature of investment | Pooled money in a diversified portfolio, managed by an AMC | A fixed-income instrument where a lump sum earns a pre-decided interest rate | Direct ownership of shares in a company |
| Returns | Market linked, depends on the fund’s portfolio and type | Fixed and known in advance | Market linked, depends on individual stock performance |
| Risk | Differs by fund type, from low to very high | Low, though returns depend on the stability of the deposit-taking institution | High, concentrated in a single stock |
| Liquidity | Depends on the scheme. Debt funds are usually processed within 24 hours on business days, equity funds usually take 1 to 3 business days | Lower, early withdrawals will cost a penalty | High, can be sold anytime during market hours |
| Diversification | High, spreads investment across multiple companies and sectors | A single deposit stays locked for a period. | Low, depends on the investor’s own stock selection |
| Management | Managed by a professional fund manager | Fixed by the bank at the time of deposit | Self-managed, requires knowledge and ongoing monitoring |
| Taxation | Depends on fund type.
Equity funds: LTCG above ₹1.25 lakh at 12.5%, STCG at 20%. Debt funds: taxed as per your income tax slab |
Interest taxed as per your income tax slab | LTCG above ₹1.25 lakh at 12.5%, STCG at 20% |
| Ideal for | Investors seeking growth, ok with some risk | Investors prefer safety and fixed returns | Investors comfortable picking and monitoring individual stocks |
Important Mutual Fund Terms
| Term | Meaning |
| NAV (Net Asset Value) | Market value of mutual fund units |
| AUM (Assets Under Management) | Total value of assets managed by a mutual fund company |
| Expense Ratio | Annual fees paid to the Asset Management Company (AMC) |
| Exit Load | A fee charged if units are sold before the lock- in period is over. |
| SIP (Systematic Investment Plan) | An option to invest a fixed amount on a regular basis. For e.g. - 15th of every month |
| Lump Sum | An option to invest an amount all at once, rather than instalments |
| Fund Manager | A professional who manages a mutual fund and makes investment decisions |
| Benchmark | A standard against which the performance of a mutual fund is measured |
| Lock-in Period | A fixed period during which an investor cannot redeem mutual fund units |
| Diversification | Distribution of an investment across different types of assets |
| Folio Number | A unique number assigned to an investor’s account with a mutual fund house, used to track their investments |
| NFO (New Fund Offer) | The period when a new mutual fund scheme is first offered to investors, typically at Rs. 10 per unit |
| Riskometer | A SEBI-mandated scale showing a mutual fund scheme’s risk level, from Low to Very High |
| STP (Systematic Transfer Plan) | An option to transfer a fixed amount from one mutual fund to another at regular intervals |
| SWP (Systematic Withdrawal Plan) | An option to withdraw a fixed amount from a mutual fund at regular intervals |
| CRISIL (Credit Rating Information Services of India Limited) |
Crisil is a rating agency that rates mutual funds and company debts |
| Fund of Funds
|
A fund that invests in a portfolio of other funds. Global mutual funds are usually Fund of international funds. |
| Holdings | The individual stocks, bonds, or other securities that a mutual fund owns. |
| Mean Returns | The average of the returns earned by a fund over a period, also called: Expected return |
| AMFI (Association of Mutual Funds in India) | a non-profit, self-regulatory organization that promotes the Indian mutual fund industry. |
Frequently asked questions on Mutual Funds
-
-
What is a mutual fund in simple words?
A mutual fund pools your money with other investors. A professional fund manager invests the pooled money in stocks, bonds, or other securities. You get fund units called NAV, for whatever you put in. So, even as an investor with a small amount you can have a diversified, professionally managed portfolio.
-
What are the 4 types of mutual funds?
Equity, debt, hybrid, and solution oriented. Equity funds go for growth, debt funds go for stability, hybrid funds split the difference. Solution-oriented funds exist for one goal, retirement or a child’s education.
-
Is a mutual fund tax-free?
No. Long-term gains above ₹1.25 lakh are taxed at 12.5%, short-term gains on equity funds at 20%, and debt funds go by your income tax slab. ELSS is the exception. It qualifies for a deduction of up to ₹1.5 lakh a year under Section 80C (under the old tax regime only)
-
What is the minimum amount to invest in mutual funds?
You can start investing in mutual funds with as little as ₹100 a month through a SIP.
-
What is the difference between SIP and mutual fund?
A SIP means investing a fixed amount at regular intervals, for example ₹100 every month. A mutual fund is the investment itself. You can put money into a mutual fund either way, through a SIP or as a lump sum.
-
Can I invest ₹5,000 in a mutual fund?
Yes. Put in ₹5,000 as a lump sum or as a SIP at ₹5,000 every month, for as long as you choose.
-
What is the difference between an ETF and a mutual fund?
Both hold a basket of securities and spread your risk across them. The difference is that ETF units trade on the stock exchange throughout the day, at live market prices, much like a stock. Whereas, Mutual fund units are bought and sold only once a day, at the NAV calculated after the market closes.
Disclaimer: Investments in the securities market are subject to market risks. Read all related documents carefully before investing. Taxes are subject to change and the most recent Finance Act should be consulted.
-